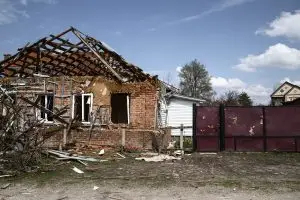
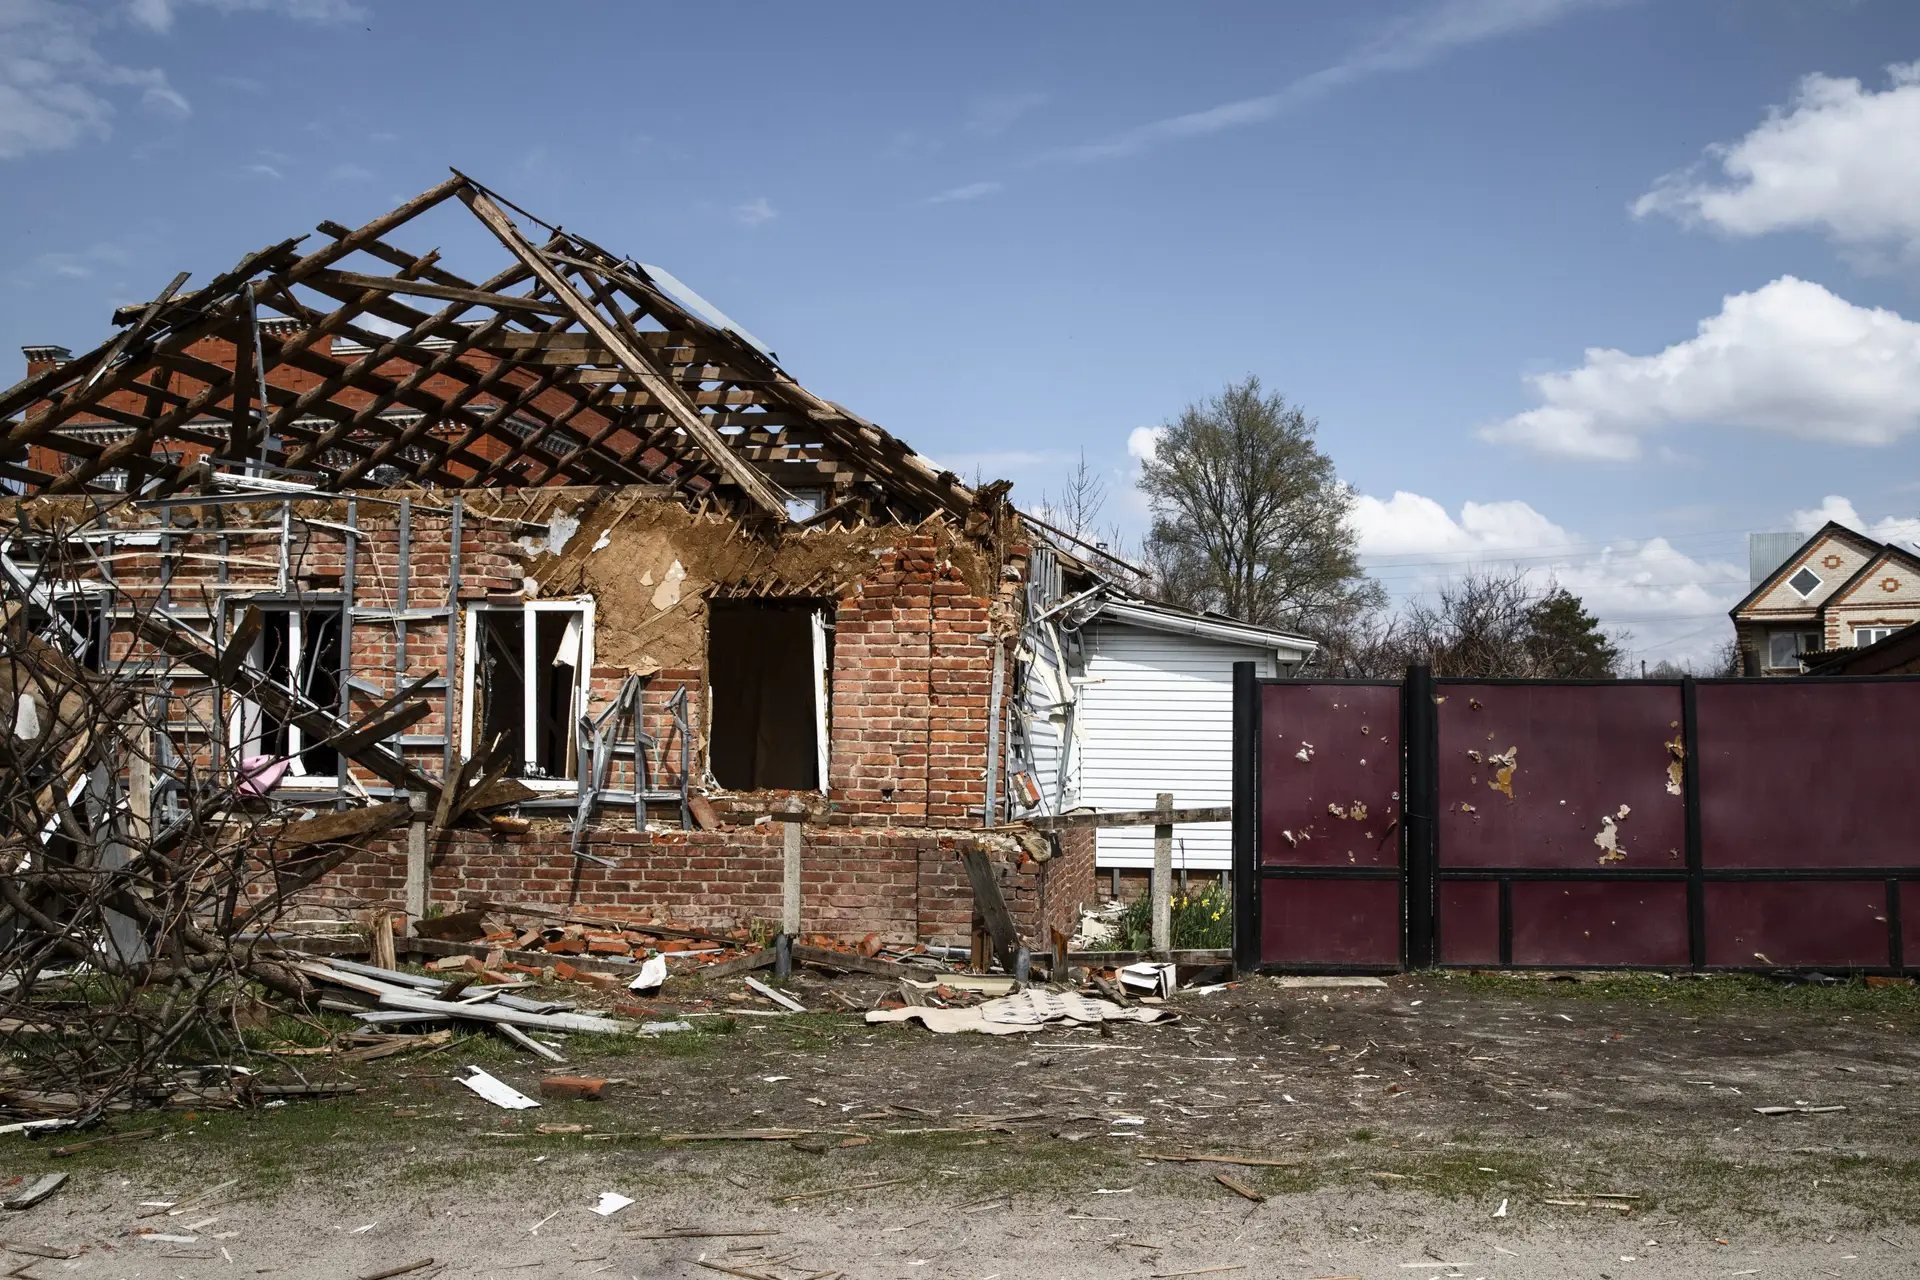
Once the insurance claim is moving, the pressure shifts to rebuilding — and that’s where some of the most expensive mistakes happen. Families are exhausted, living out of a rental, and eager to get home. Contractors know it.
At Purity Homes, we design, scope, and budget homes in the Nine Mile Falls and greater Spokane area. These are the ten rebuilding mistakes we see most often, and how to avoid them.
Home Building Mistakes to Avoid When Rebuilding After a House Fire
After a big fire, out-of-area crews flood in with flyers, door knocks, and promises to start next week. Some are legitimate. Many disappear once the deposit clears or the work gets hard.
Verify every contractor’s license, bond, and insurance on Washington L&I’s Verify a Contractor tool. Ask for local references and addresses of homes they’ve finished. Never hand over a large deposit before work starts.
Reusing the foundation without testing it
Reusing the old foundation looks like an easy way to save money. But intense heat can weaken concrete and rebar in ways you can’t see from the surface.
Have a structural engineer evaluate it before you design around it. If it fails, you want to know before framing starts — not after. And if it passes, get that report in writing for your permit file and your insurer.
Cutting corners on debris and ash cleanup
Fire debris isn’t just burned wood. Ash can contain heavy metals, asbestos from older materials, and residue from plastics, batteries, and household chemicals.
Use a qualified debris removal contractor and wear proper protection if you visit the site. Make sure the pad is fully cleared down to clean soil before any new work begins. A rushed cleanup can mean contaminated soil under your new home.
Rebuilding the old floor plan by default
It’s natural to want your old home back exactly as it was. But you’ll likely never have a cleaner chance to fix what didn’t work: the cramped kitchen, the missing mudroom, the bedroom that was always too cold.
Spend a little time on design before you lock in plans. Small layout changes cost very little on paper and a lot once walls are framed. Just confirm with your insurer how changes in size or layout affect what they’ll pay.
Skipping fire-resistant construction
In eastern Washington, wildfire isn’t a one-time event. Rebuilding the same way leaves you exposed to the same risk — and may make insurance harder to get down the road.
Most homes ignite from embers, not a wall of flame. The upgrades that help most are often modest:
- Class A roofing, like metal or rated composition shingles
- Ember-resistant vents for attics and crawlspaces
- Noncombustible siding and trim near the ground, and fire-rated deckingDual-pane, tempered glass windows
- A 5-foot noncombustible zone around the house — gravel, not bark mulch Planning these in from the start costs far less than retrofitting later.
Signing a vague contract with no detailed scope
A one-page bid that says “rebuild 2,000 sq ft home — $450,000” is an invitation for surprises. Without a written scope, you can’t tell what’s included, what’s an allowance, and what will turn into an extra charge later.
Insist on a line-item scope of work that spells out materials, finishes, allowances, and who handles permits and site work. It protects you, it gives your adjuster something to compare against, and it holds every trade to the same standard.
Underestimating Permits, Design, and Construction Timelines
Many families assume construction starts as soon as the lot is clear. In reality, drawings, engineering, permits, and septic or well approvals can take months before the first footing is poured — longer when a whole community is rebuilding at once.
Build a realistic schedule from day one and compare it to when your living-expense coverage runs out. Getting design and permit work started early is one of the best ways to protect that coverage.
Forgetting the well, septic, power, and site work
On rural lots, a big share of the rebuild cost lives outside the house. Melted well lines and pressure tanks, septic systems crushed by cleanup equipment, burned power poles, and damaged driveways all need to be repaired or replaced.
Have each system inspected early and get it into your scope and budget. These items are easy to miss on a quick estimate — and expensive to discover halfway through the build.
Making Changes Mid-Build During Home Construction
Moving a wall, upgrading cabinets, or adding a window after framing starts can ripple through the whole schedule. Every change order brings new costs, re-ordered materials, and trades coming back to redo work.
Make your big decisions — layout, finishes, fixtures, and appliances — before construction begins. Choosing selections early also lets your builder order long-lead items so they arrive on time.
No Contingency Fund and Payments Out of Sync with Insurance
Every rebuild runs into something unexpected: bad soil, a failed foundation, a price jump on materials. A budget with no cushion turns a small surprise into a stalled project. Plan a contingency of 5–10% of construction cost.
Also, match your contractor’s payment schedule to how your insurer releases money. Many insurers hold back part of the claim until work is done, and your mortgage lender may be named on the checks too. Pay for completed work in stages — never far ahead of it.
Rebuild with a plan
At Purity Homes, every fire rebuild starts the same way: a clear design, a detailed line-item scope, and a realistic budget and schedule — before a single trade shows up on site. That’s how we keep projects on track and give families a home that’s better than the one they lost.
If you’re starting a rebuild, reach out for a no-pressure conversation about your lot, your plans, and your budget.
(509) 350-2021 / paul@purityhomes.net / https://purityhomesnw.com/
This article is general information, not legal, engineering, or insurance advice.